Loading
- Home
- About Tradex
- Products & Services
- Foodservice
- Seafood News
- School of Fish
EP 805 | AIRED 08/10/2026
China Seafood Market Update: Groundfish Diverges. Wild Salmon Prices Climb. | August 2026
August 10, 2026 - Chinese seafood processing markets remain mixed, with groundfish showing divergent trends while salmon markets continue to strengthen. Our recommendation is to look beyond the headline price trends, as several key species are beginning to diverge, creating both procurement risks and buying opportunities highlighted in this report.
Atlantic cod has continued to weaken as raw material prices decline. Russian headed-and-gutted fish is now trading below $9,000/MT, while Norwegian raw material prices have fallen by more than $1,000/MT over the past month. Despite lower pricing, buyer interest remains muted, reflecting adequate inventories and a cautious purchasing approach.
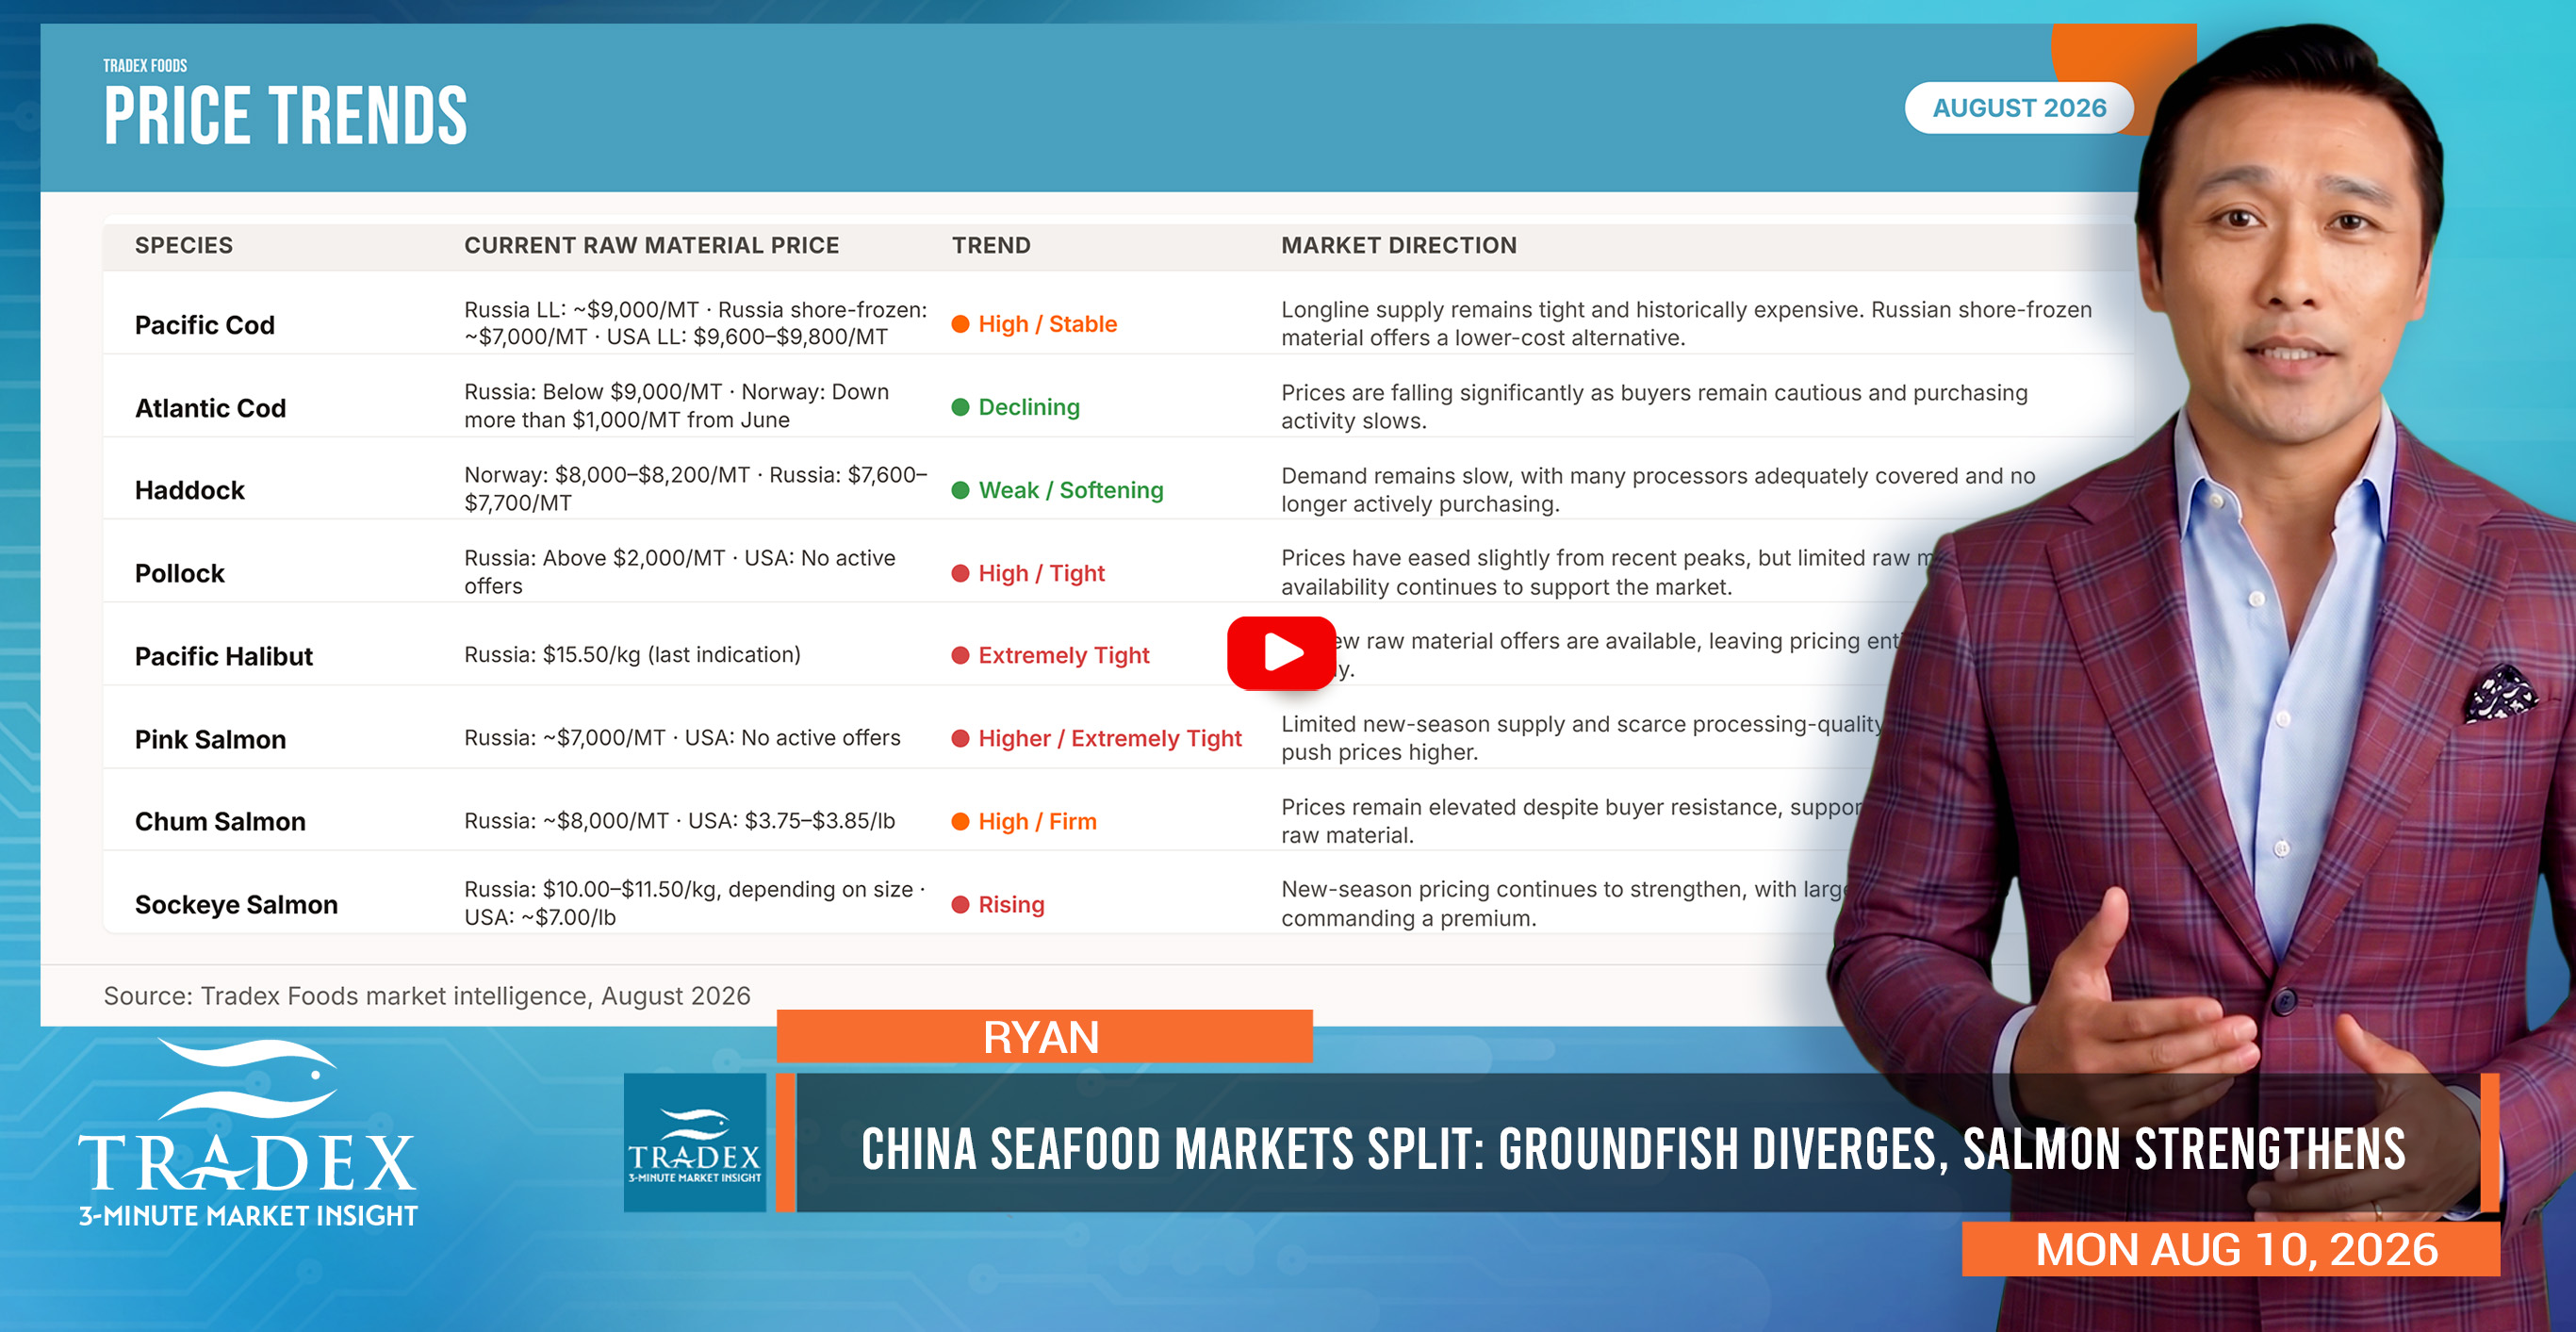
Haddock remains the weakest segment of the groundfish market. Norwegian raw material is quoted around $8,000–8,200/MT, while Russian product is trading near $7,600–7,700/MT. Market activity remains slow, with many processors indicating they have sufficient inventory and do not expect to purchase additional headed-and-gutted raw material this year.
Pollock fundamentals remain firm despite earlier price corrections. Russian raw material continues to trade above $2,000/MT with limited availability, while U.S. raw material remains effectively unavailable due to high pricing. Finished pollock fillets continue to hold around $2.00/lb FOB China, and migas pricing remains above $5,000/MT FOB China as processors compete for scarce raw material.

Advertise Here: advertising@tradexfoods.com
Pacific halibut remains one of the tightest markets, with no new Russian raw material offers reported. The last market indication remains approximately $15.50/kg, and finished product pricing continues to be driven entirely by raw material availability.
Wild salmon markets continue to strengthen as new-season supply remains limited. Pink salmon remains exceptionally tight, with Russian raw material now offered around $7,000/MT and no meaningful U.S. offers available. Processors report that limited inventories of quality fish continue to support higher finished product pricing.
Chum salmon has also strengthened. Russian raw material is being offered around $8,000/MT, while U.S. 4–6 lb SBB fish is quoted at approximately $3.75–3.85/lb. Although buyers have shown resistance to these higher prices, limited availability of quality raw material continues to support the market.
Sockeye salmon prices continue to trend higher as the new season progresses. Russian raw material is quoted at approximately $10.00/kg for 1.0–1.8 kg fish and $11.50/kg for 1.8–2.5 kg fish, while U.S. raw material is reported around $7.00/lb. Market sentiment remains bullish as buyers compete for new-season production.
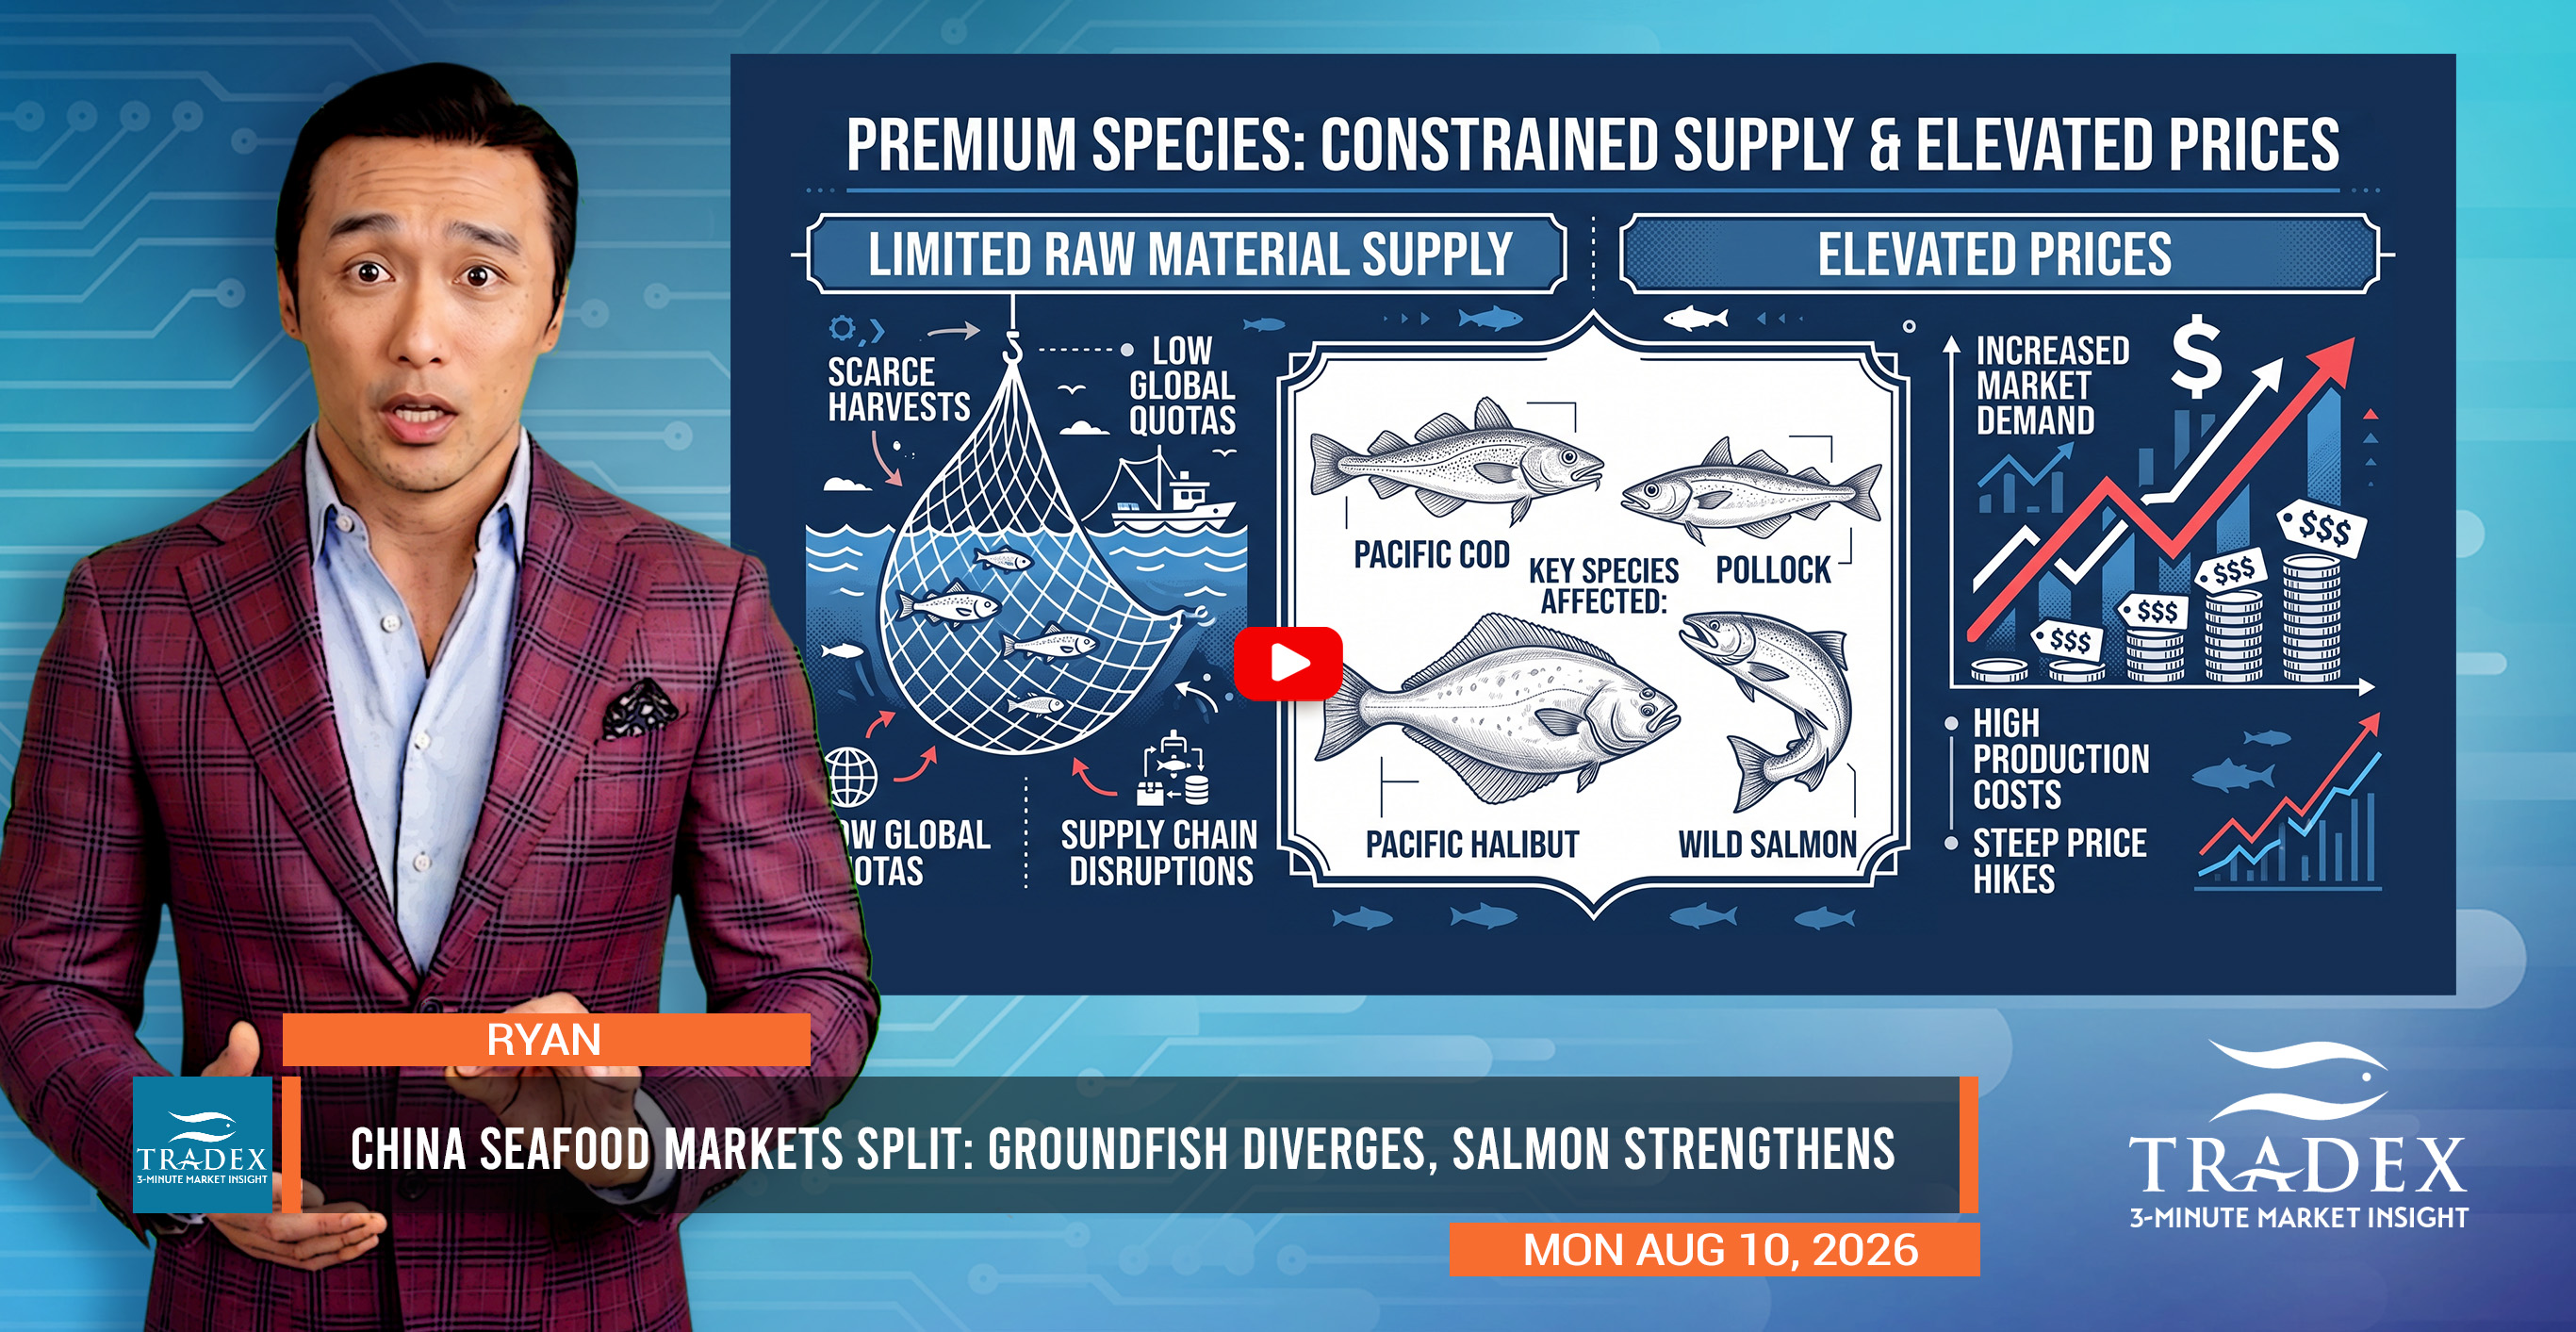
Overall, premium species—including Pacific cod, pollock, Pacific halibut, and wild salmon—remain constrained by limited raw material supply and elevated prices. Our recommendation is to secure coverage early, as supply is expected to remain tight and pricing firm in the near term. Conversely, Atlantic cod and haddock continue to soften as demand eases and inventories improve, creating opportunities for buyers to purchase selectively or delay larger commitments in anticipation of further price weakness.
--- If you’re not already, be sure to subscribe to our 3-Minute Market Insight for seafood updates and insights delivered right to your inbox.