Loading
- Home
- About Tradex
- Products & Services
- Foodservice
- Seafood News
- School of Fish
EP 807 | AIRED 08/24/2026
Pollock Market Update: Raw Material Prices Push Higher as Supply Remains Tight
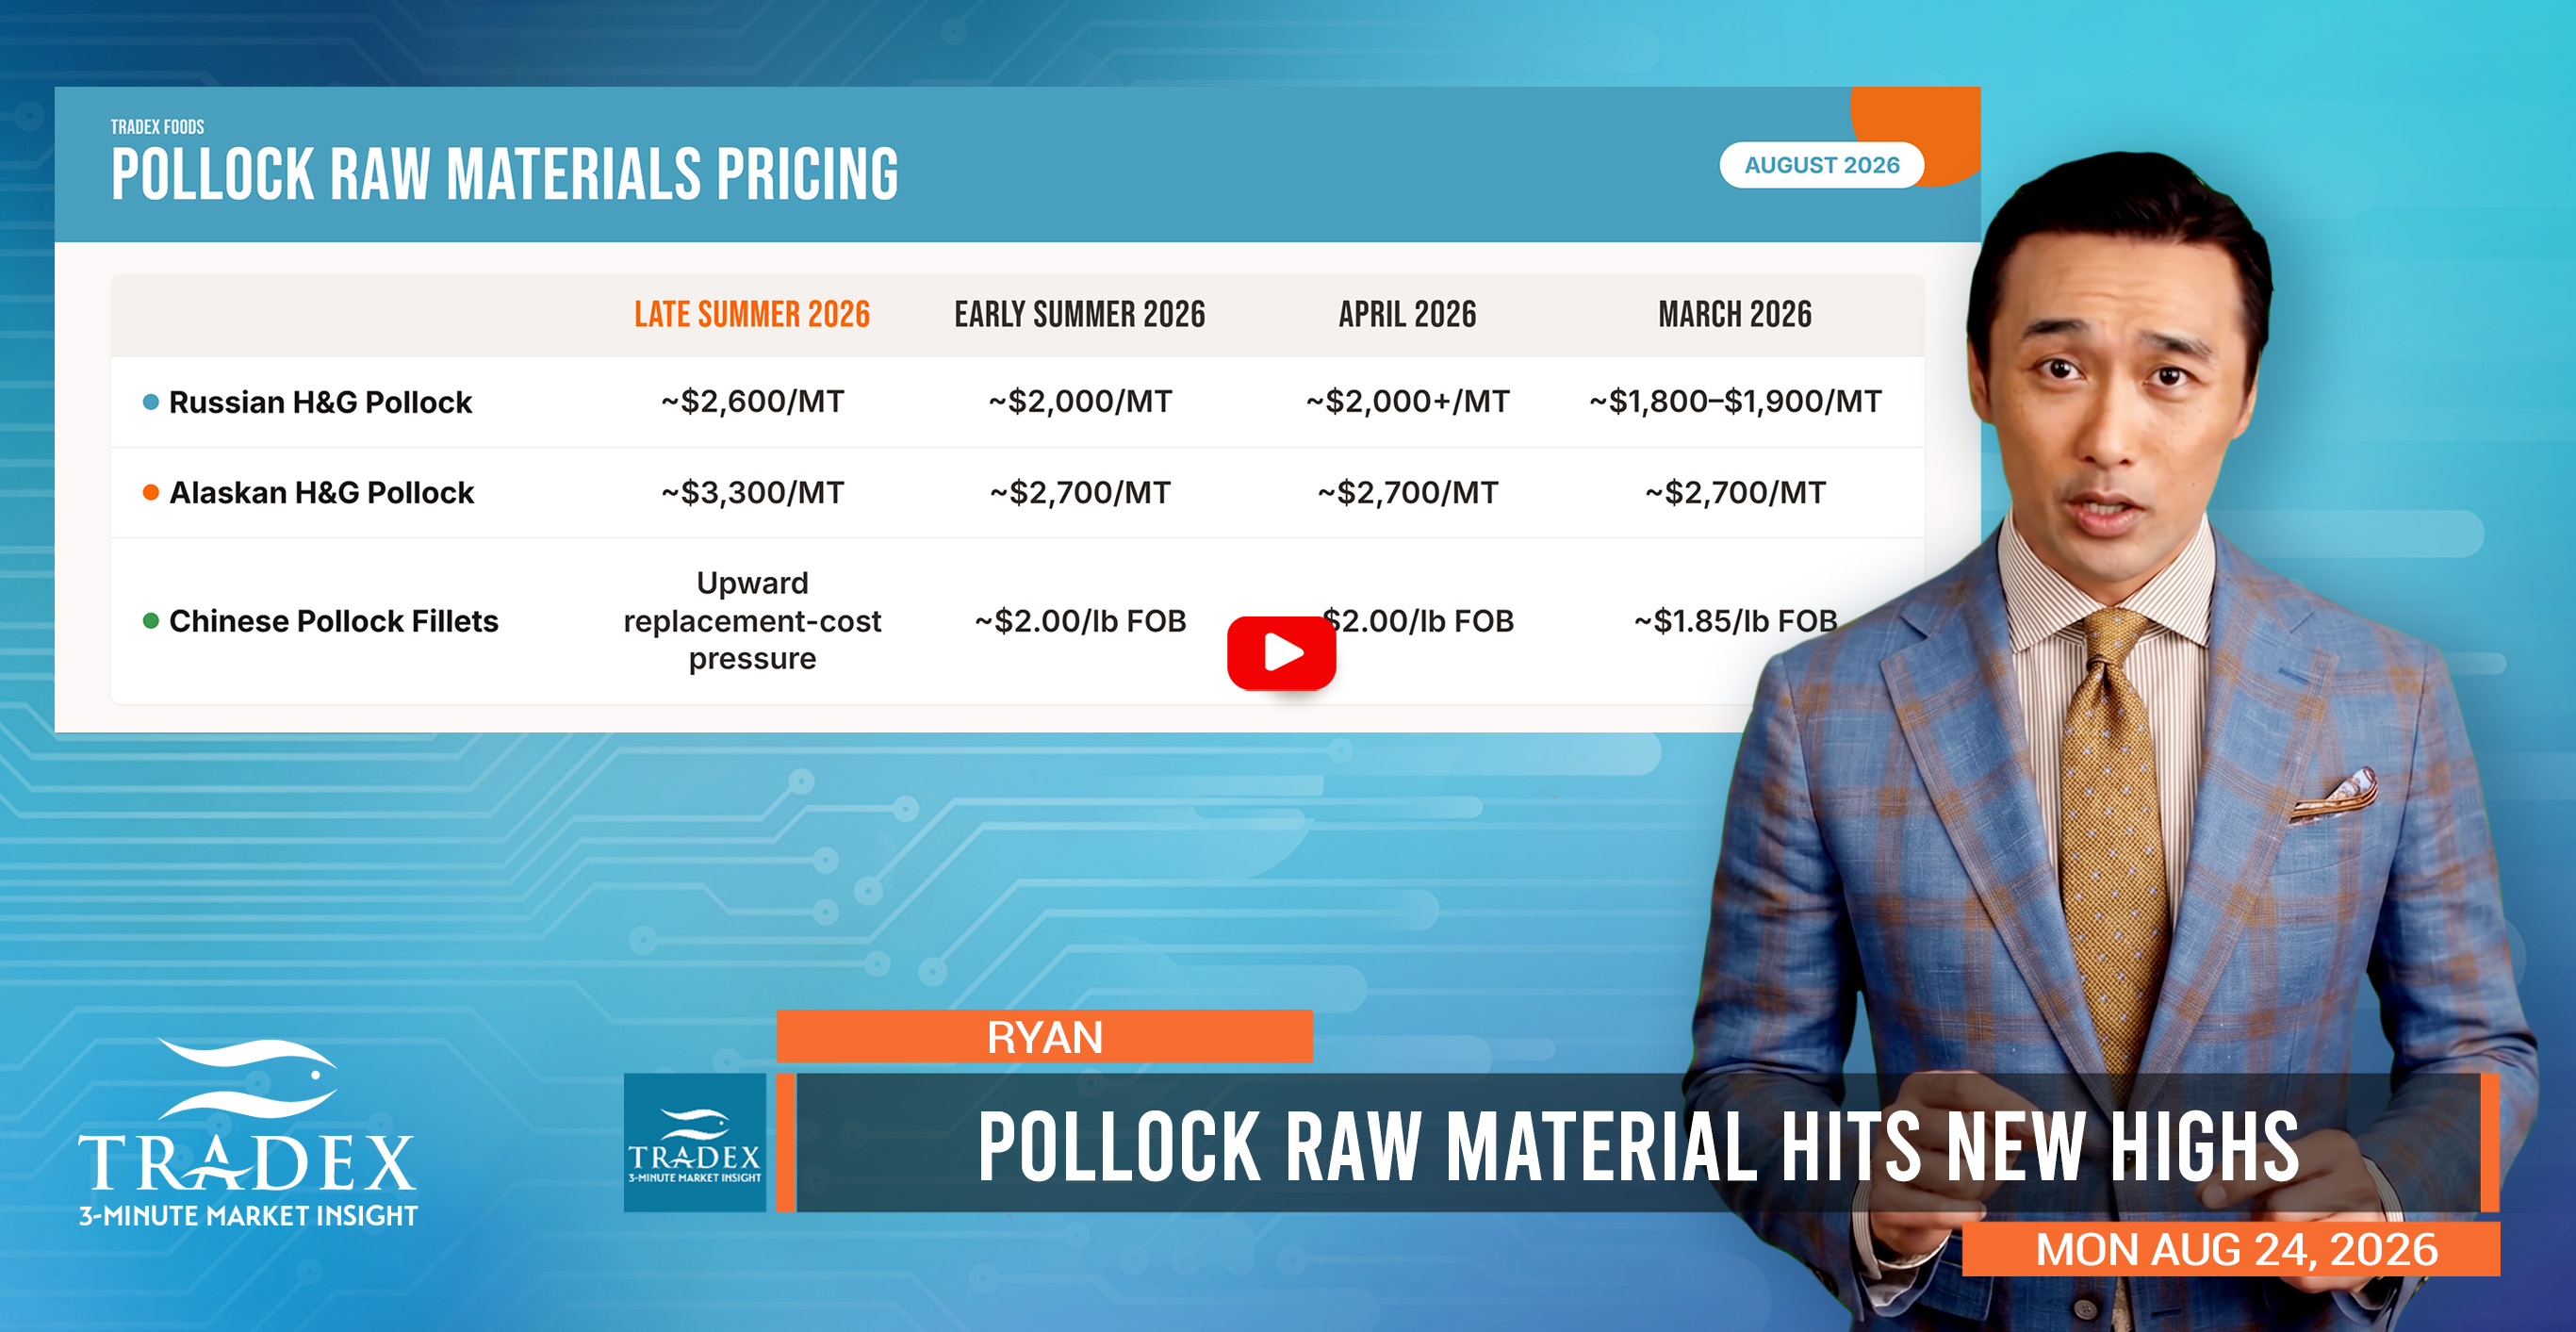
August 24, 2026 - The global pollock market remains exceptionally firm as Chinese processors compete for limited H&G raw material. Current market indications out of China put Russian H&G pollock at around $2,600 per metric ton and Alaskan H&G at around $3,300 per metric ton. These should be viewed as approximate market levels rather than exact transaction prices, as values can vary by size, specification and supplier.
Russian raw material has risen considerably from earlier in the year. Prices were approximately $1,800–$1,900 per metric ton in March and around $2,000 per metric ton through much of the spring and early summer. According to Undercurrent News’ Week 34 assessment, Russian 25cm+ H&G pollock reached another record, with demand continuing to outpace available supply.
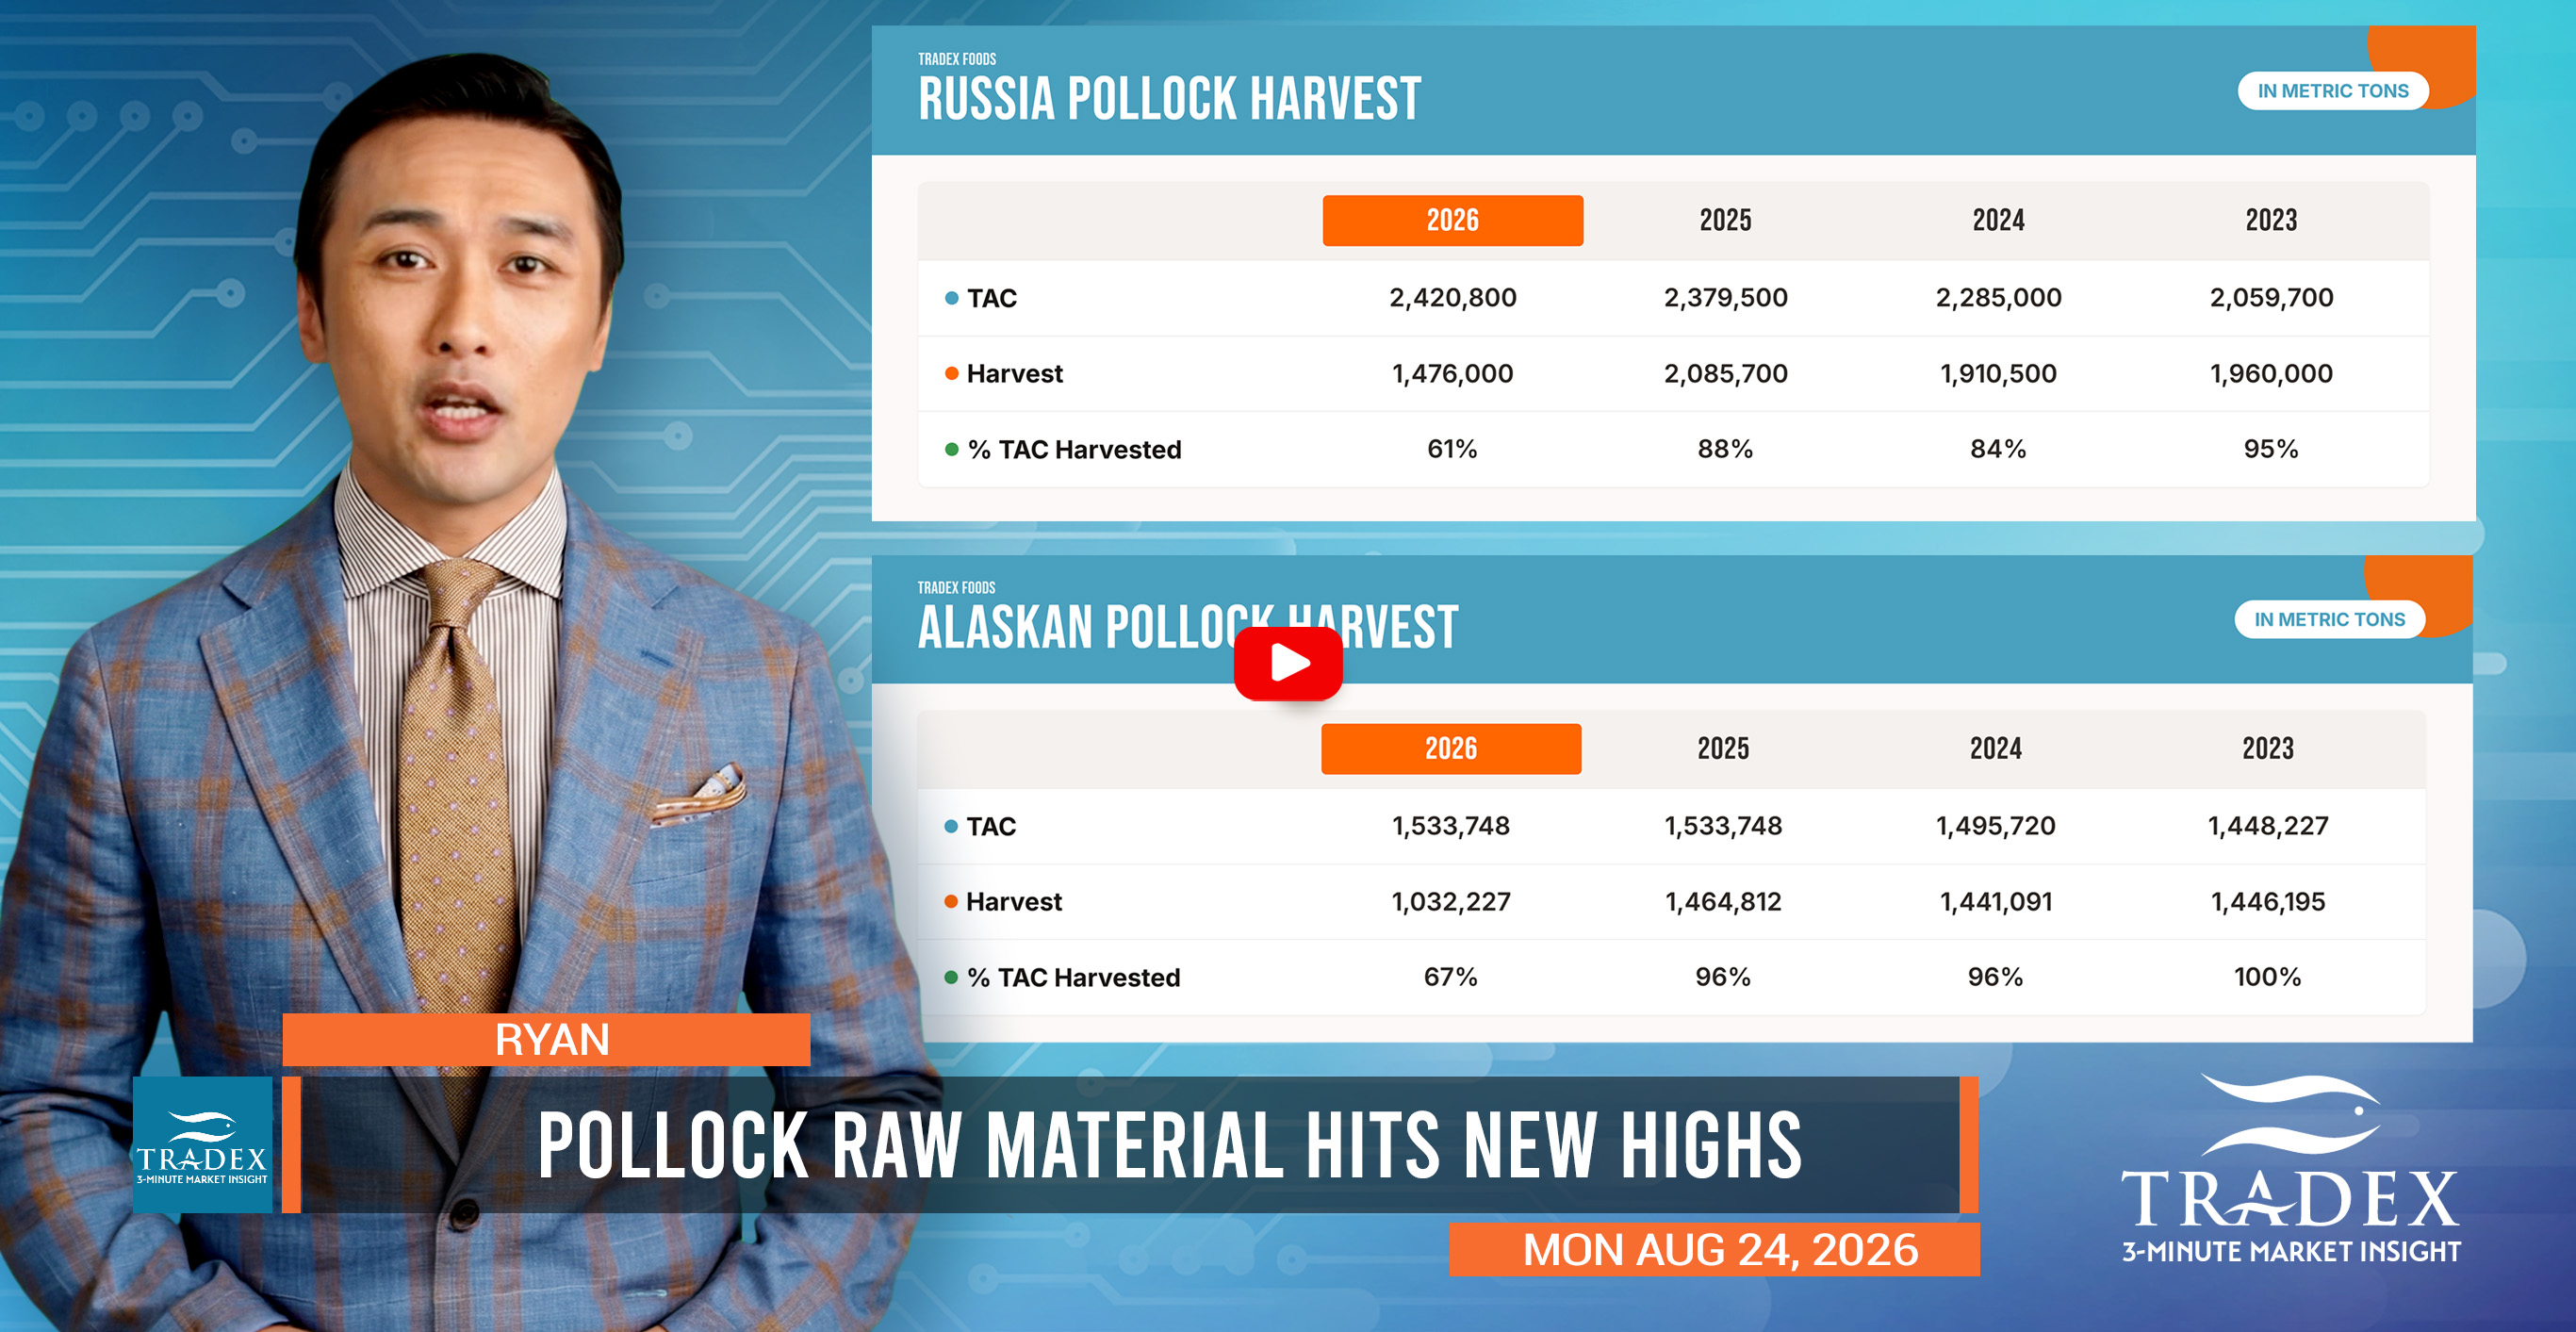
The harvest numbers show why headline catch alone does not tell the full story. Russia had harvested approximately 1.476 million metric tons of pollock as of August 10, against a 2026 TAC of roughly 2.421 million metric tons. As reported by UCN, Russian H&G production through early August was approximately 451,000 metric tons, about 2% behind the comparable 2025 period, while Chinese raw-material use and finished-product exports have increased considerably. The combination of slightly lower H&G production and stronger Chinese processing activity is keeping usable raw material tight despite the substantial overall Russian harvest.
Trade restrictions are further segmenting the global market. Russian-origin pollock cannot enter the United States even when processed in a third country such as China, limiting the ability of US-bound programs to substitute Russian fish for higher-priced Alaskan supply. Europe can still use Russian-origin pollock, but its exclusion from reduced-duty EU tariff quotas makes Russian fish less attractive for some European buyers. These restrictions leave certain markets more dependent on Alaskan and other compliant origins while directing more Russian supply toward China and other accessible destinations.

Advertise Here: advertising@tradexfoods.com
Alaska is experiencing similar price pressure even though quota availability has remained relatively stable. The combined 2026 BSAI and GOA commercial pollock TAC is approximately 1.534 million metric tons, including roughly 1.394 million metric tons in the BSAI and 139,500 metric tons in the GOA. The current Alaskan H&G indication of around $3,300 per metric ton, compared with approximately $2,700 per metric ton from March through early summer, therefore appears to reflect tight usable raw-material availability, processing economics and replacement demand rather than a major reduction in headline quota. Restrictions on Russian-origin fish also reduce lower-cost alternatives for US-bound programs.
Higher raw-material costs are beginning to create additional pressure on finished products. Chinese pollock fillets were approximately $1.85 per pound FOB China in March, rising to around $2.00 per pound by April and remaining near that level into early summer. With Russian H&G now indicated around $2,600 per metric ton, maintaining those finished-product levels will become increasingly difficult as processors work through lower-cost inventories and replace them with more expensive raw material.
The key issue for buyers is therefore not simply how much pollock is being harvested, but how much usable H&G raw material is available relative to demand and where that material can legally and economically be sold. Russian H&G production is slightly behind the comparable 2025 period, Chinese processing activity remains strong, and stable Alaskan TAC has not prevented Alaskan raw-material prices from rising approximately $600 per metric ton, or 22%, from the $2,700 level seen earlier this year.
Our Recommendation is to cover confirmed near-term requirements while keeping longer-term positions flexible, as tight H&G availability, strong Chinese demand and restrictions on Russian-origin supply continue to support firm pollock pricing.
--- If you’re not already, be sure to subscribe to our 3-Minute Market Insight for seafood updates and insights delivered right to your inbox.