Loading
- Home
- About Tradex
- Products & Services
- Foodservice
- Seafood News
- School of Fish
EP 808 | AIRED 08/31/2026
2026 Wild Salmon Outlook: Alaska Recovers as Russia Supply Falls Short
August 31, 2026 - The 2026 North Pacific wild salmon season is entering its final major production phase with substantially less salmon reaching the market than last year and the previous even-numbered season. Alaska has experienced a meaningful August recovery; however, Russia remains significantly behind expectations, while the outlook for Japan's fall chum season suggests little additional supply relief.
Alaska Salmon Harvest Improves Following August Pink Recovery
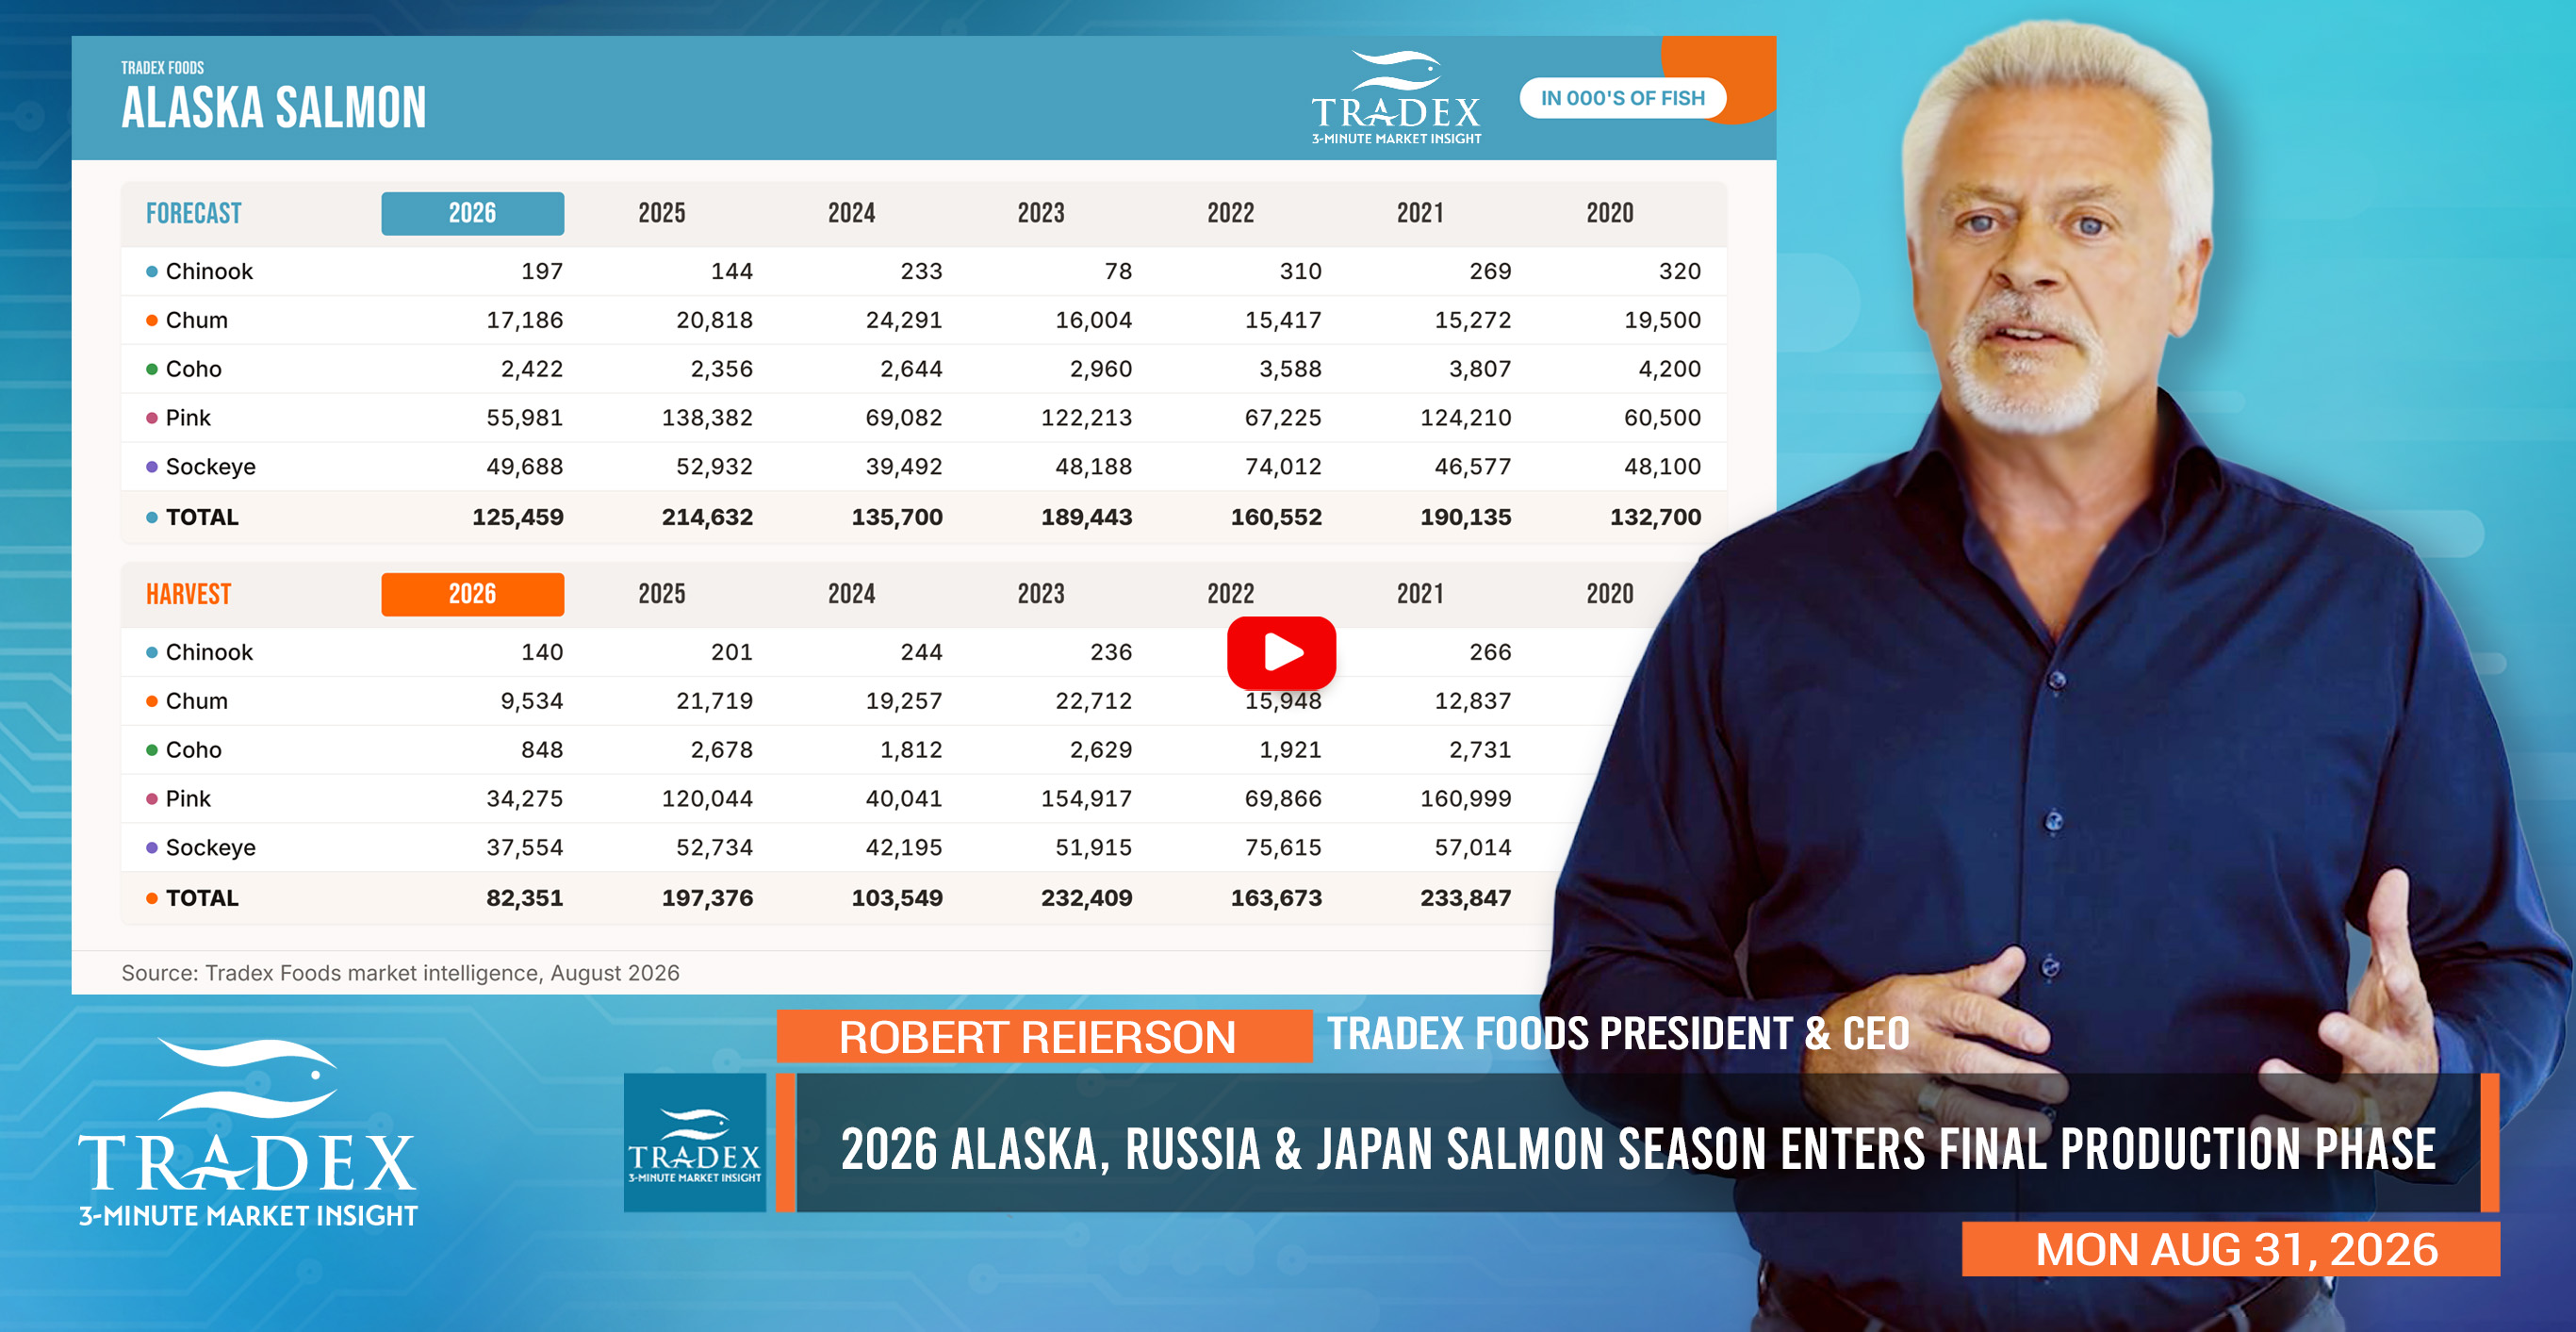
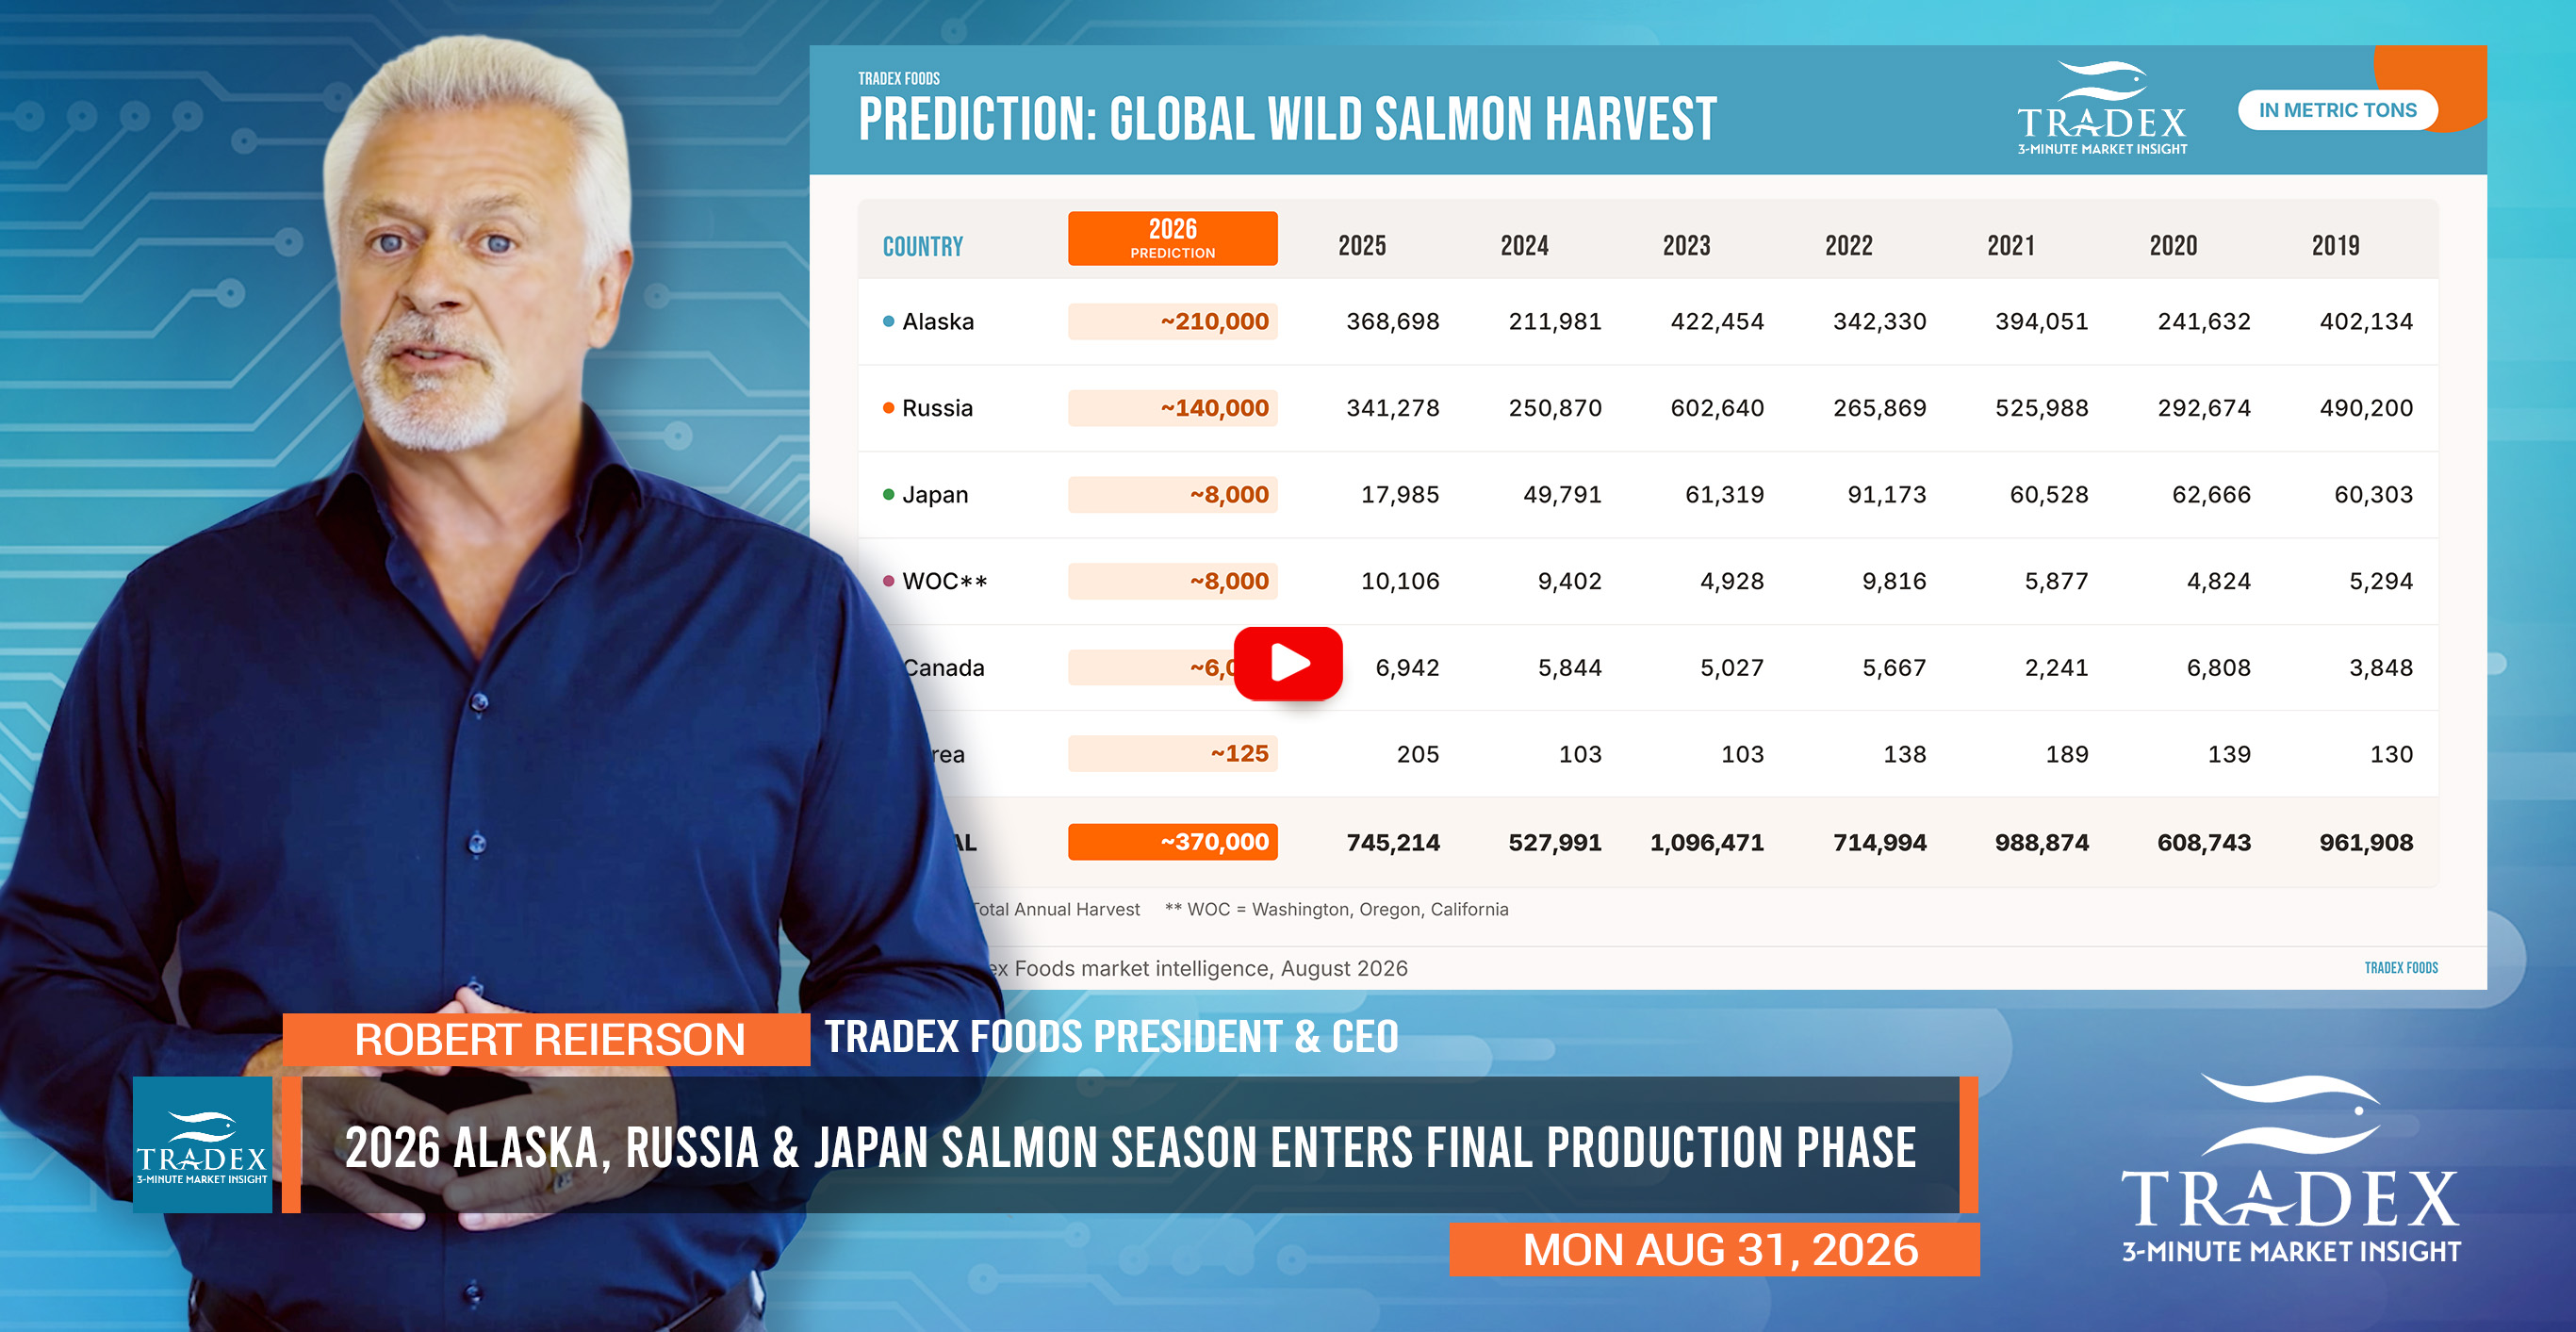
Alaska's statewide commercial salmon harvest has reached just over 80 million fish, representing approximately 65% of its 125.5 million-fish preseason forecast. Sockeye and pink salmon account for the majority of production, with approximately 38 million sockeye and 34 million pink salmon harvested. The largest development has been the strong August recovery in pink salmon, particularly from Southeast Alaska and Kodiak. This has materially improved the supply outlook compared with earlier in the summer; however, Alaska was still running approximately 50% behind 2025 around Week 35. Based on the current species mix and remaining fishing opportunity, Alaska could finish the 2026 season near 210,000 MT, compared with approximately 360,000 MT in 2025 and 200,000 MT in the previous even-numbered 2024 season.
Russia Remains the Greater Supply Concern
Russia's Pacific salmon harvest has reached approximately 90,000 MT, representing about 40% of its revised 231,000 MT forecast. Pink salmon accounts for approximately 41,000 MT, followed by about 25,000 MT of chum, 19,000 MT of sockeye and 3,000 MT of coho. Pink salmon remains the primary concern, with production approximately 69% below the comparable 2024 level and recent harvest additions slowing considerably. With the major pink production window largely behind the fishery, remaining Russian production is increasingly dependent on late-season chum and coho. Based on the current trajectory, Russia could finish near 140,000 MT, compared with approximately 335,000 MT in 2025 and 235,000 MT in 2024, representing a significant reduction in available Russian wild salmon supply.
Supply Shortfall Extends Beyond the Normal Pink Salmon Cycle
Combined Alaska and Russian production could finish near 350,000 MT, approximately 50% below 2025 and 20% below the previous even-numbered 2024 season. The comparison with 2024 is particularly important because it indicates that the 2026 supply reduction extends beyond the normal odd/even pink salmon production cycle. Trade restrictions further tighten accessible supply, as Russian salmon cannot offset Alaska shortages in the U.S. market and is increasingly concentrated in markets where imports remain permitted. This could contribute to greater regional differences in wild salmon availability and replacement costs. Time for either country to materially close the production gap is also becoming limited. Alaska has approximately one to two meaningful weeks of broad production remaining, followed by increasingly regional chum and coho fisheries, while Russia has approximately three to five meaningful production weeks remaining, with most incremental volume expected from chum and coho.

Advertise Here: advertising@tradexfoods.com
Supply Shortfall Extends Beyond the Normal Pink Salmon Cycle
Attention will increasingly shift toward Japan as the Hokkaido fall chum season develops. The latest Hokkaido forecast calls for a return of only 3.65 million chum salmon, approximately 47% below the already record-low 2025 return.
Based on the current outlook, Japanese fall chum harvest could finish near 8,000 MT. Although relatively small compared with Alaska and Russia, another weak Japanese season could have an outsized effect on the salmon roe market, potentially increasing Japanese competition for limited Alaskan and Russian chum and roe supplies.
2026 Wild Salmon Harvest Outlook
The current 3MMI harvest outlook projects approximately 210,000 MT from Alaska, 140,000 MT from Russia and 8,000 MT from Japan, for roughly 360,000 MT combined by the end of their respective seasons.
Alaska's August recovery has improved availability considerably; however, Russia's substantial shortfall and another potentially weak Japanese fall season indicate that the broader North Pacific wild salmon market remains tight. Pink salmon, chum, canned salmon programs and salmon roe are among the categories most exposed to reduced supply as the remaining production window closes.
Our Recommendation is that buyers protect near-term pink salmon, chum and roe requirements, as remaining fall production is unlikely to replace the substantial volume of wild salmon missing from the market in 2026.
--- If you’re not already, be sure to subscribe to our 3-Minute Market Insight for seafood updates and insights delivered right to your inbox.