Loading
- Home
- About Tradex
- Products & Services
- Foodservice
- Seafood News
- School of Fish
EP 811 | AIRED 09/21/2026
China Seafood Processing Update: Cod and Haddock Soften as Other Markets Stay Tight
September 21, 2026 - China’s seafood-processing market remains sharply divided, with Pacific cod and pollock supported by tight supply, Atlantic cod and haddock weakening amid limited demand, and wild salmon prices remaining exceptionally high. Our recommendation is to watch these market signals closely, as the best buying opportunities and greatest replacement-cost risks are now moving in opposite directions.
Atlantic cod continues to move lower. Russian H&G raw material is now below $9,000/MT, while Norwegian prices have fallen by more than $1,000/MT compared with last month. Despite the decline, buyers remain reluctant to purchase, suggesting the market correction is being driven primarily by weak demand rather than a meaningful recovery in supply. This creates a more favorable environment for buyers that can remain patient and selective.
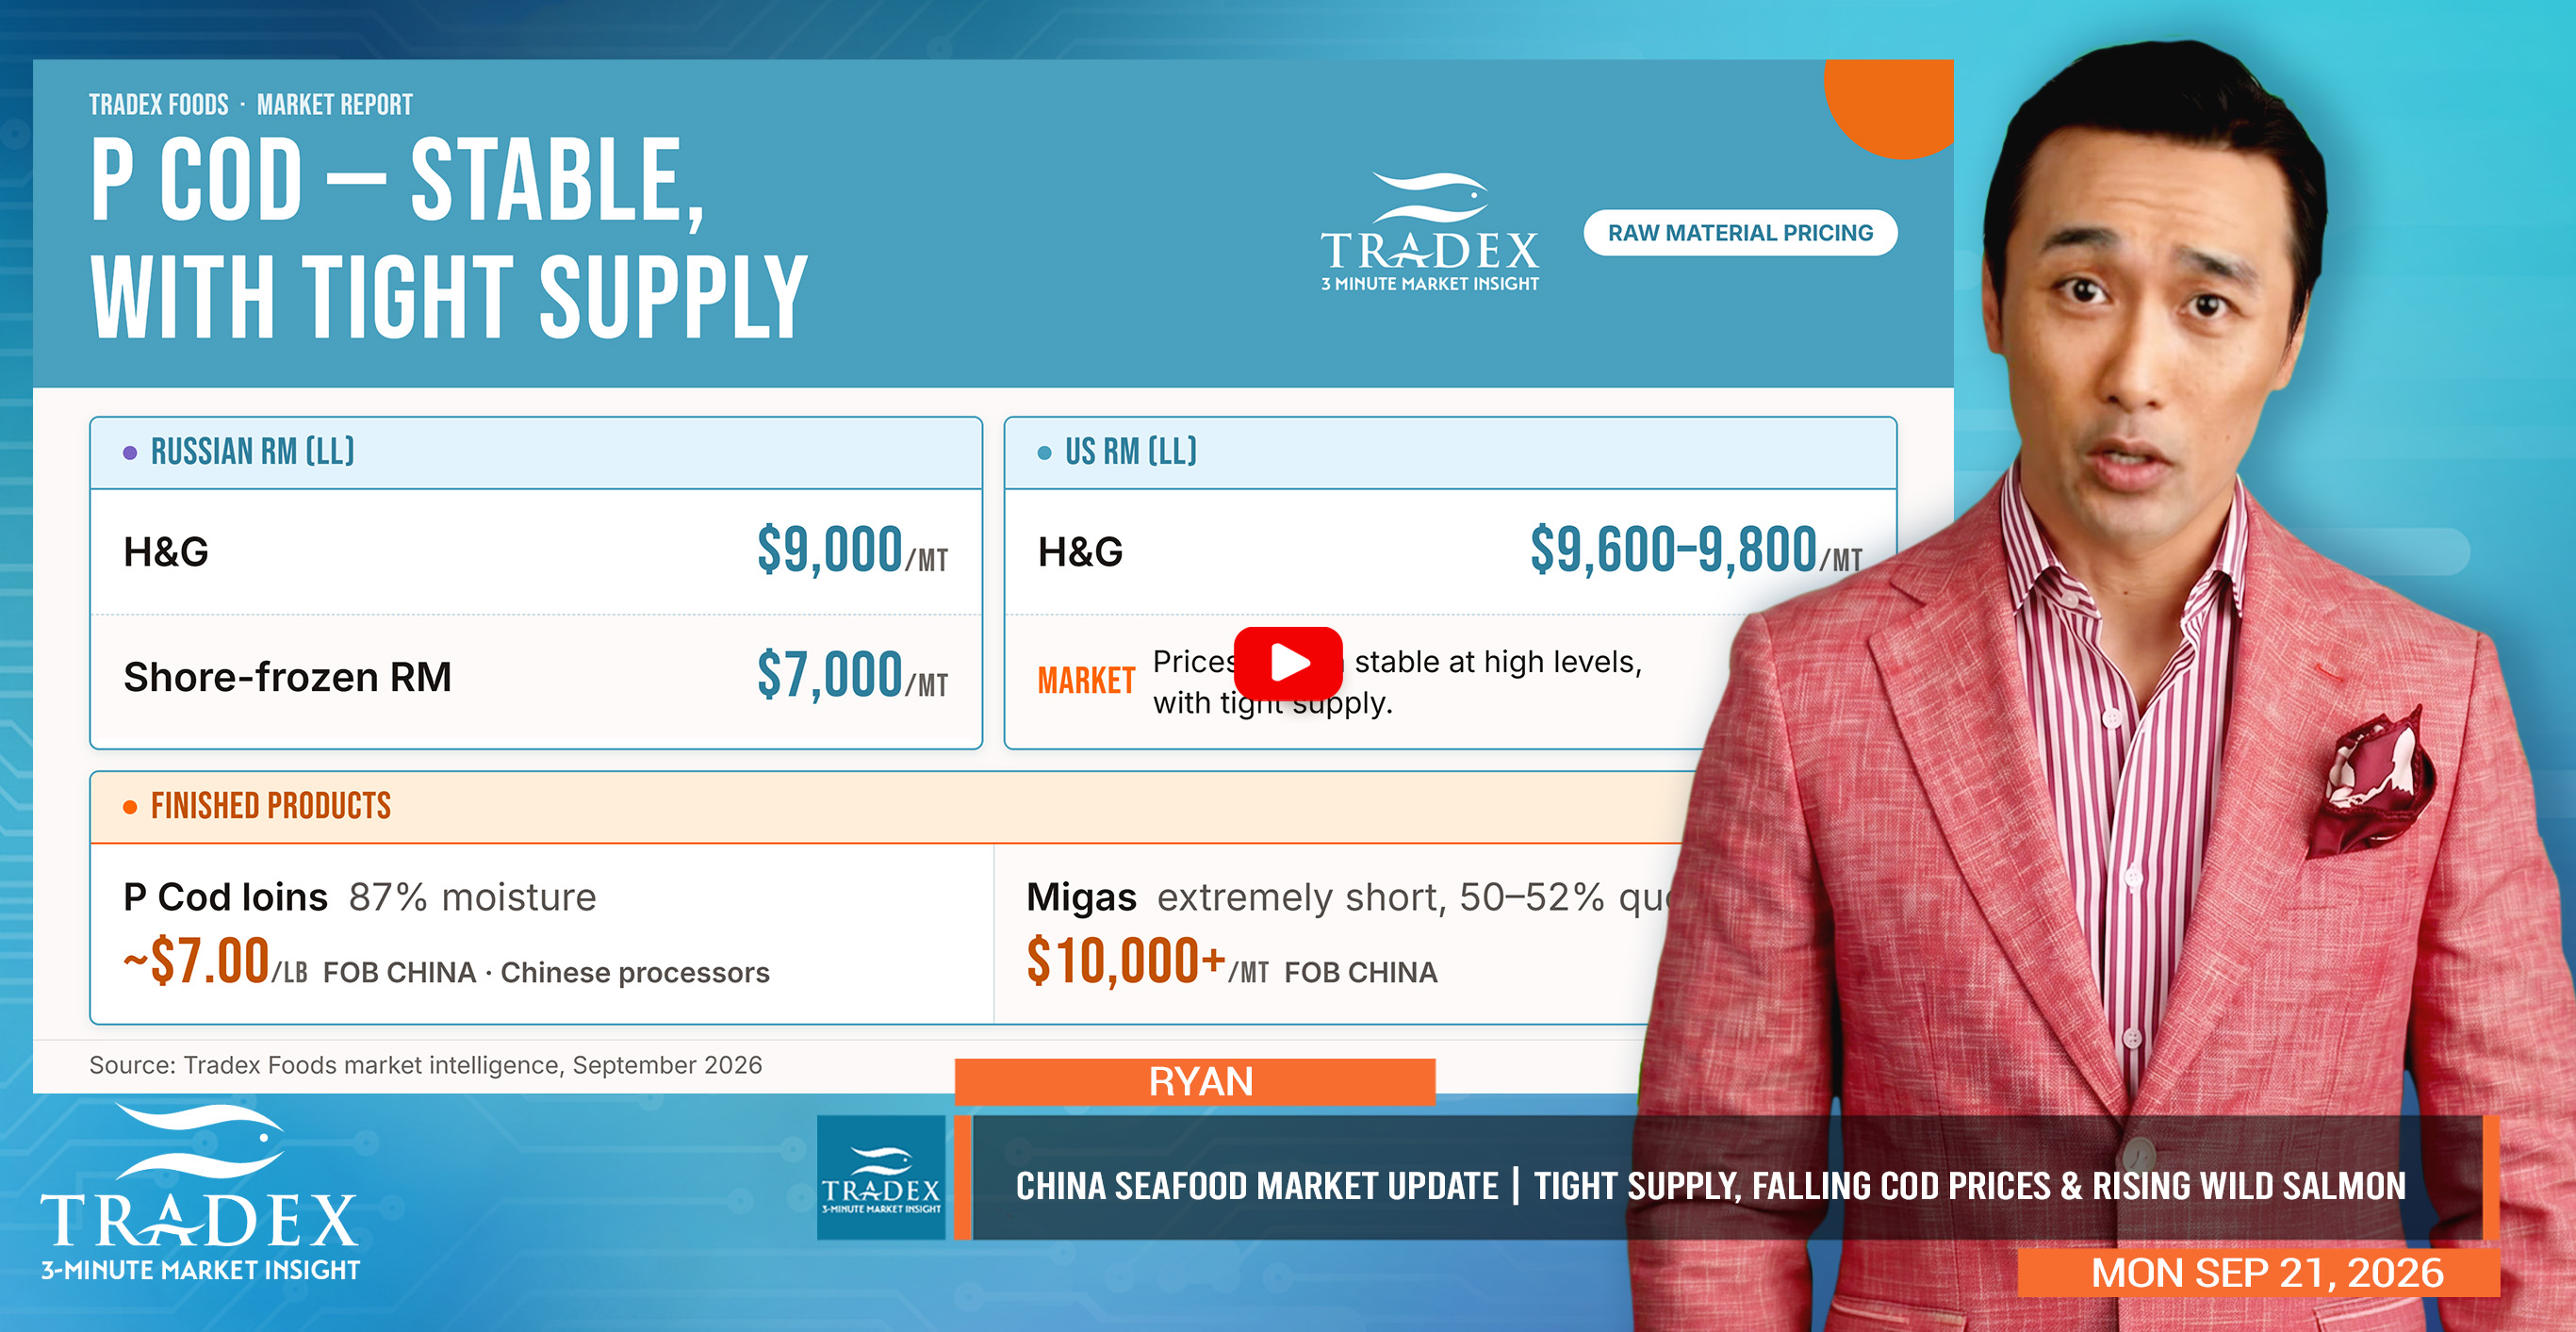
Haddock is showing similar weakness. Norwegian raw material is indicated around $7,600/MT, while Russian material is approximately $7,000/MT. However, these levels are largely reference prices because active buying remains limited. Many processors indicate they do not expect to purchase additional haddock H&G this year, reinforcing the soft demand outlook and potential for continued downward pressure.
Pollock remains one of the strongest groundfish markets. Russian H&G raw material is around $2,600/MT, with limited availability, while U.S. material was last indicated near $3,300/MT but is effectively absent from the Chinese market at that level. Raw material tightness continues to support replacement costs. Pollock fillets at 89% moisture remain around $2.00/lb FOB China, while 50–52% migas is quoted above $5,000/MT FOB China.
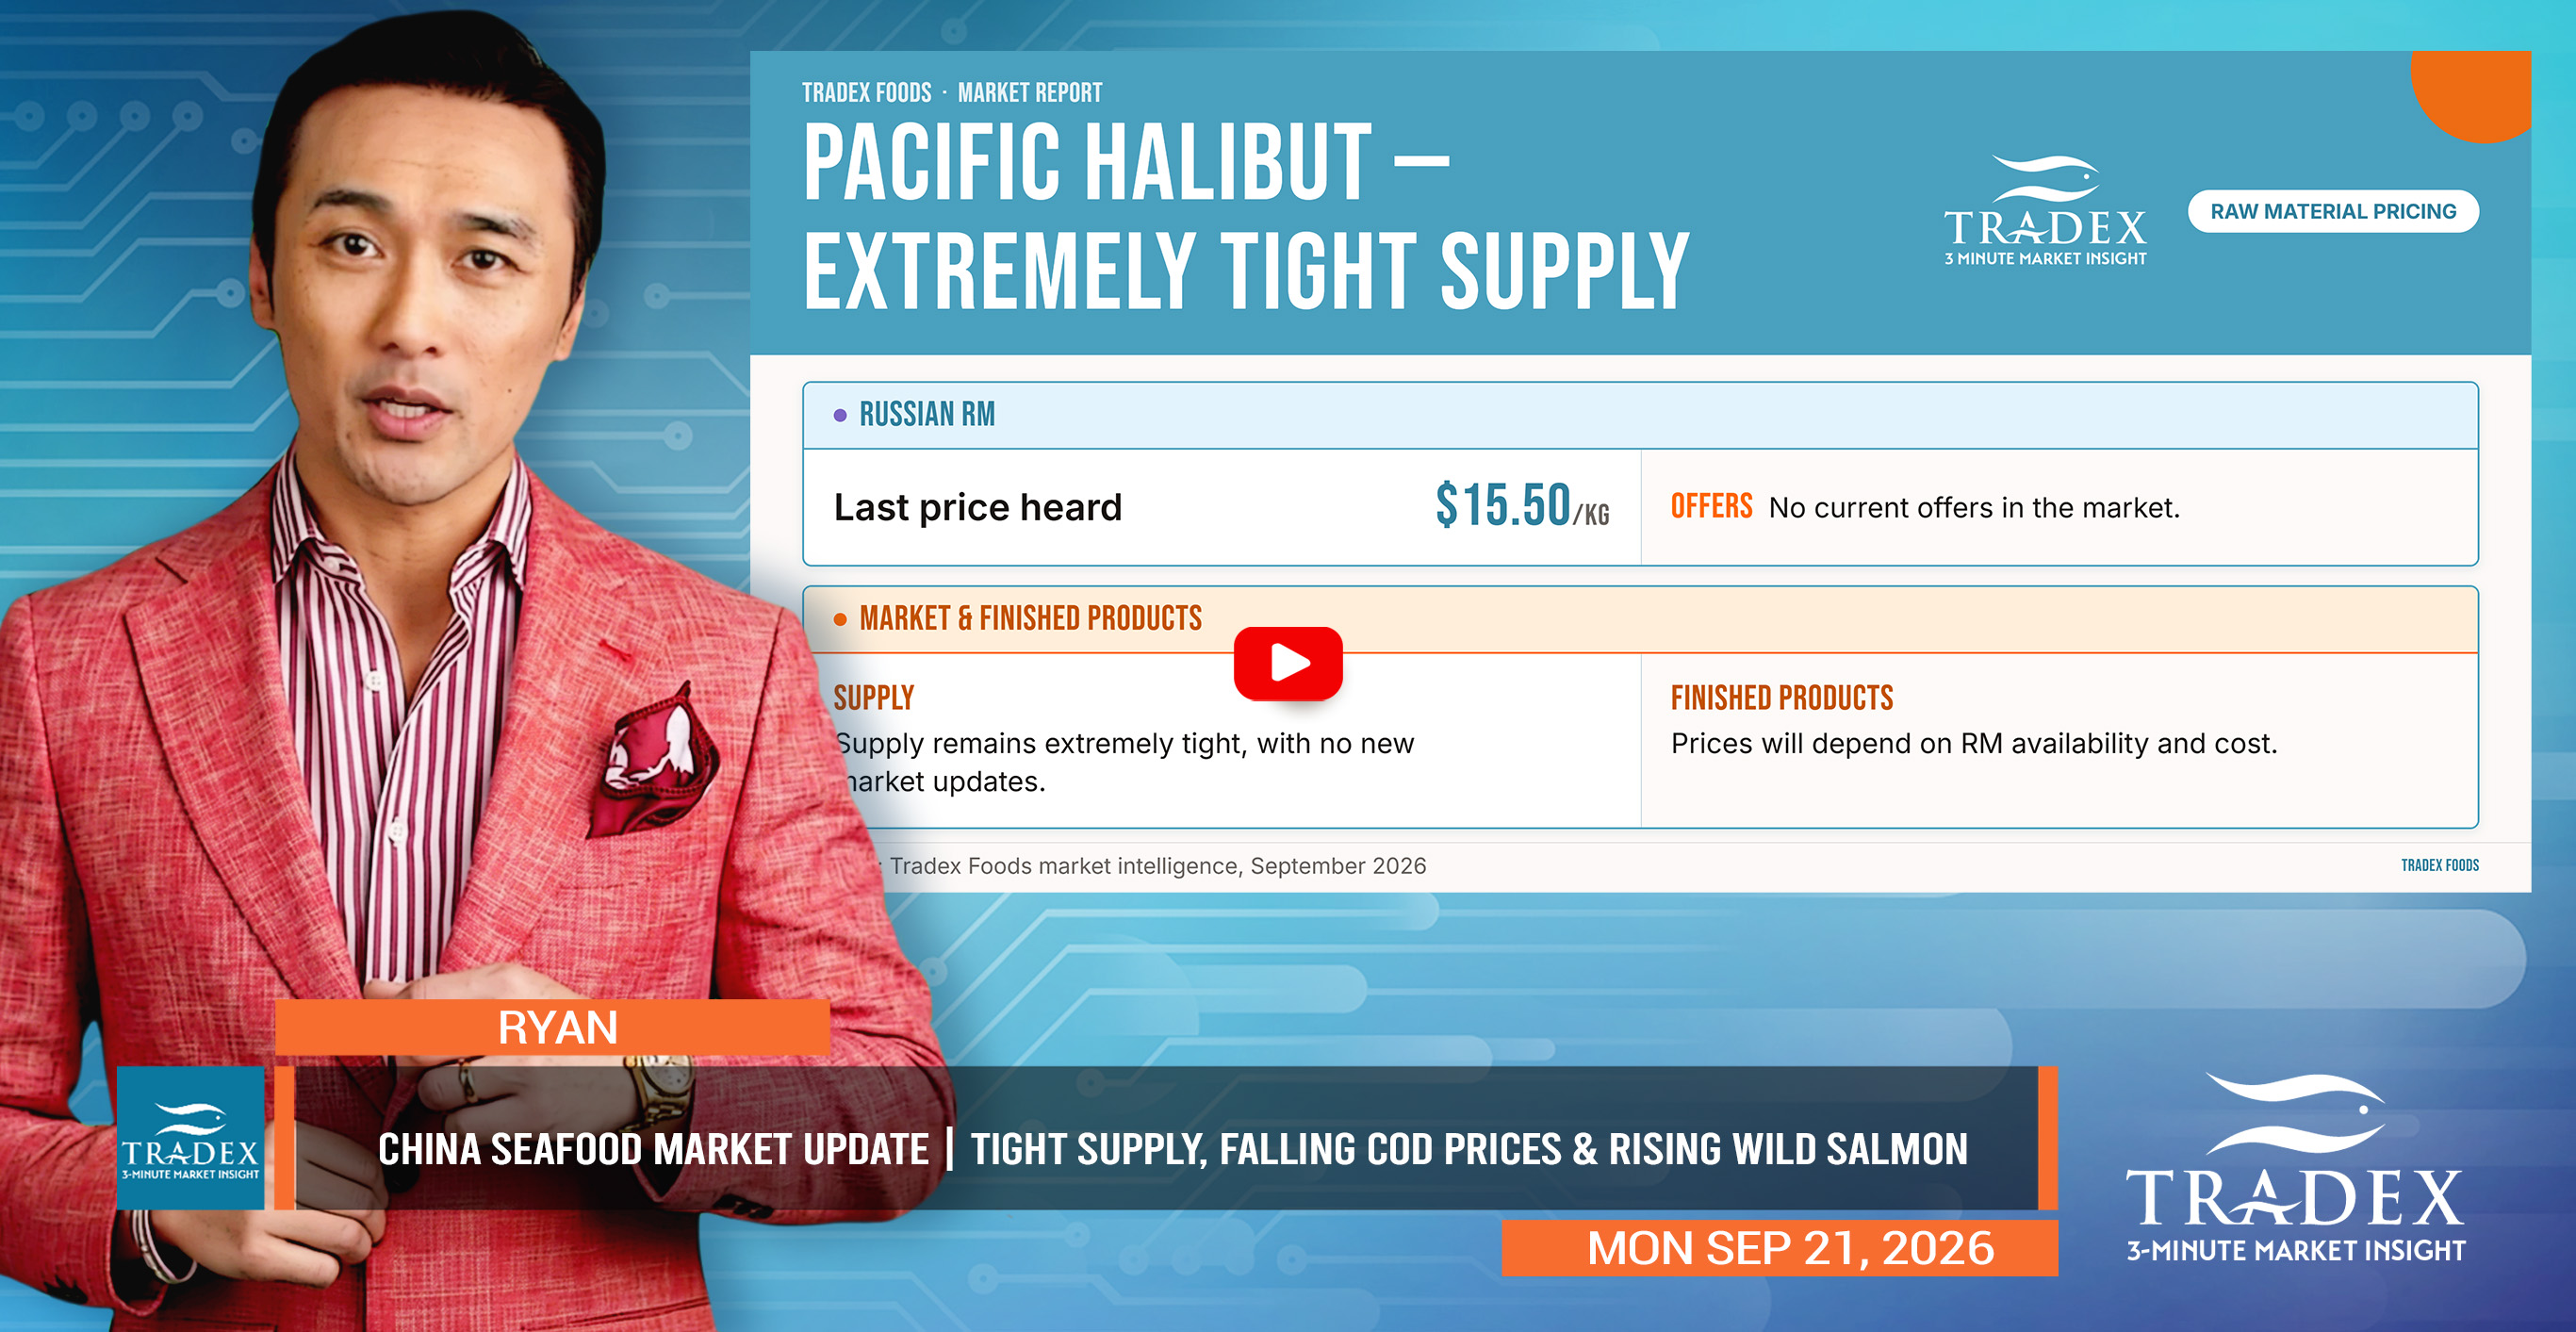
Pacific halibut supply remains extremely tight, with no current Russian raw material offers. The last market indication was approximately $15.50/kg, and finished-product pricing continues to depend entirely on raw material availability and replacement cost. With little new market activity, the category remains highly supply-driven.
Advertise Here: advertising@tradexfoods.com
Wild salmon continues to show the strongest upward price pressure. Russian pink salmon H&G is now offered around $9,000/MT, while U.S. supply remains short with no active offers. Good-quality raw material is becoming increasingly difficult for processors to secure, supporting further increases in finished-product pricing.
Chum salmon is also elevated, with Russian raw material offered around $9,000/MT and U.S. material indicated at approximately $4.00–$4.20/lb. Buyers continue to resist the highest Russian offer levels, but processors are finding it increasingly difficult to source suitable quality fish for production. As with pink salmon, limited good-quality raw material remains the primary driver of the market.
Overall, the China processing market is increasingly split between demand-driven weakness in Atlantic cod and haddock and supply-driven strength in Pacific cod, pollock, Pacific halibut, pink salmon and chum salmon. This divergence is creating very different procurement conditions depending on species.
Our recommendation is to remain patient on Atlantic cod and haddock, where weak demand may create additional buying opportunities, while protecting near-term requirements for Pacific cod, pollock, pink salmon and chum salmon, where tight raw material availability continues to support elevated replacement costs.
--- If you’re not already, be sure to subscribe to our 3-Minute Market Insight for seafood updates and insights delivered right to your inbox.